Living in California you’re well aware of the threat of quake damage, even if you don’t live near the most notorious fault lines. Yet you might not know that in order to be covered for damage from an earthquake you’ll need to purchase a separate earthquake policy or an available earthquake endorsement as a companion to your homeowners policy.
- Quake coverage isn’t included by default with homeowners policies, but your carrier is required to offer you an option to purchase every other year.
- In California over 1.5 million residential earthquake policies are in force and the California Earthquake Authority (CEA) is the most popular choice.
- The average homeowner earthquake policyholder in California in 2025 pays about $120 a month with average coverage of $889,000. That can be higher or lower based on factors like the earthquake risk of your location, characteristics of your home like foundation type, age, and number of stories, as well as the deductible and coverage you choose.
What does quake insurance cover?
The base dwelling coverage of an earthquake policy covers damage to your home caused directly by an earthquake, including:
- Foundation cracks
- Structural damage to walls, ceilings, and floors
- Damage to chimneys, though typically with capped limits
- Damage to stucco walls and with some policies exterior masonry
- Damage to walkways and patios required to enter your home
- Damage from landslides immediately triggered by the quake
It does not typically cover:
- Flood damage caused by a tsunami triggered by the earthquake (flood insurance can cover this)
- Fire damage (your homeowners insurance typically covers this)
- Damage to the soil or land your home sits on, except for limited amounts to stabilize the soil
- Damage to landscaping
Not always included but available (sometimes for an extra premium):
- Loss of use. You can also pay extra for ‘loss of use’ coverage to handle the cost of renting temporary housing while your home is being repaired.
- Other structures. The CEA covers attached garages and certain outside features, but generally not detached garages or separate structures, but won’t cover pools and spas. Some other carriers offer detached-structure and pool coverage for an extra premium.
- Personal contents. Damage to items inside your home can also be covered for an extra premium.
Your homeowners policy won’t cover any of these expenses from an earthquake unless you add a companion earthquake policy or an available earthquake endorsement.
What about FEMA?
- FEMA home-repair assistance has limits that depend on the disaster declaration date, and as of 2026 maxes out at $44,800. and federal disaster loans cap out at $500,000. We run through FEMA scenarios in detail here.
- Our illustrative estimates for a modest 2,500 square foot home range from $250,000 – $800,000 in repair costs, depending on the damage level based on a UC Berkeley analysis detailed below.
- Repairs can take months to years in some cases, and FEMA rental assistance has separate eligibility, amount and duration rules.
A quake insurance policy can help you avoid dipping into your investments or taking on what amounts to the payments on a second mortgage via an SBA disaster loan.
What deductible to choose?
Earthquake insurance deductibles are typically stated in a percent of the coverage amount like 10% instead of a round dollar amount like $10,000.
Over half of California homeowners insured by the California Earthquake Authority (CEA) in 2022 opted for a 15% deductible, translating to a $120,000 deductible for an $800,000 policy.
Deductible Options and Considerations:
- The CEA offers deductibles ranging from 5% to 25%. Other insurers like GeoVera and Palomar offer lower options, as low as 2.5%. Lower deductibles equate to higher premiums.
- On an $800,000 home, the deductible would be:
- 2.5%: $20,000
- 5%: $40,000
- 10%: $80,000
- 15%: $120,000
- 20%: $160,000
- You don’t have to pay the deductible to the insurer before receiving a payment. It is subtracted from your covered damage. Your home doesn’t have to be destroyed for a claim to pay, but you remain responsible for the portion insurance doesn’t cover. Policy limits and claim-settlement terms still apply.
Factors to Determine Your Affordable Deductible:
- Emergency Savings: A higher deductible is feasible if you have a substantial emergency fund to cover the deductible and initial recovery costs including temporary housing.
- FEMA assistance. You might also qualify for federal assistance after a major quake which can sometimes be used to cover the shortfall a deductible creates, though the federal estimate for damage might be lower than your estimate because FEMA only looks at the cost to return a home to basic living standards. Your insurance will look at the cost to return your home to its prior standard.
- FEMA repair-assistance limits depend on the disaster declaration date; as of 2026 the maximum grant available is $44,800 for essential repairs. Rental assistance for temporary housing does not use up the capped repair allowance.
- Federal disaster loans. These are available at rates set by SBA’s statutory formula, with lower rates for borrowers who cannot obtain reasonable credit elsewhere. The max loan amount is $500,000 and like a mortgage must be repaid or you can lose your home.
How much does earthquake damage cost?
When figuring the coverage and deductible of a quake policy you’ll want to have an informed conversation with a licensed insurance agent.
To help with that discussion we reviewed a 2020 UC Berkeley study that conducted a simulation of earthquake damage of common home types in California based on four earthquake scenarios (including Northridge, a 7.0 in San Francisco, a 6.8 in San Bernardino, and 6.5 in Bakersfield). The study had insurance adjusters estimate the cost to repair various damage states that occurred in the simulation.
Based on data from that study and assuming a basic 2,500 square foot tract home, we estimate the following earthquake repair costs depending on the severity of damage from cosmetic to full replacement:
- Cosmetic damage: $21,875 – $46,875
- Significant finish damage (drywall, chimney), no structural damage: $53,125 – $106,250
- Replace interior and exterior finishes (drywall, siding, chimney): $250,000 – $331,250
- Replace entire structure: $625,000 – $743,750
How did we get those figures?
The Berkeley study estimated repair costs in 2019 dollars per square foot were:
- Cosmetic damage: $7-$15 / square foot
- Significant finish damage, no structural damage: $17-$34
- Replace interior and exterior finishes (drywall, siding, chimney), some structural damage: $80-$106
- Replace entire structure: $200-$238
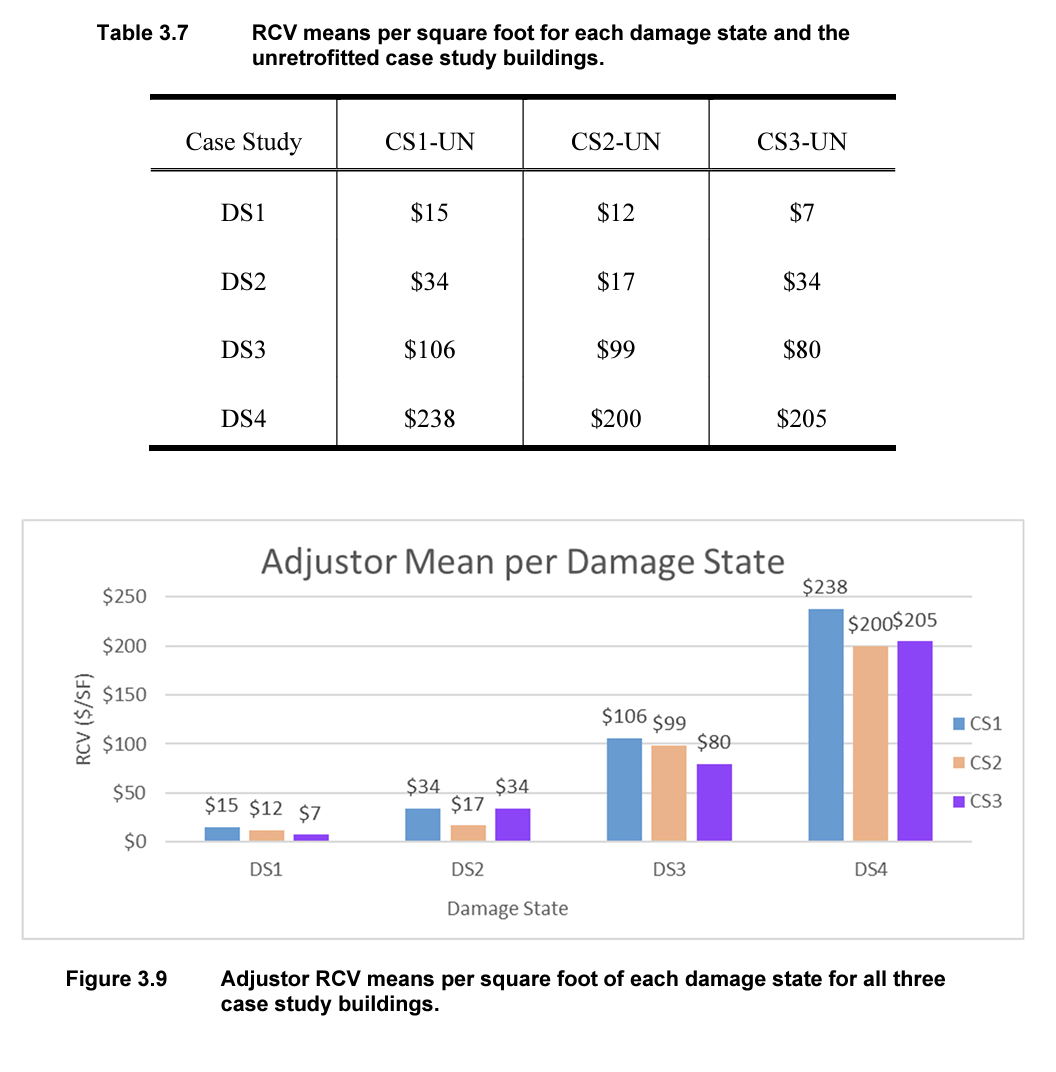
Assuming a 25% increase in costs to consider inflation since 2019, more modern finishes, and the possibility of a surge in costs after a large quake, we estimate repair costs of:
- Cosmetic damage: $9-$19 / square foot
- Significant finish damage, no structural damage: $21-$42
- Replace interior and exterior finishes (drywall, siding, chimney): $100-$132
- Replace entire structure: $250-$298
We then multiplied those square foot costs by 2,500 square feet to get the damage repair estimates.
You can use the square footage of your home to get a rough estimate and have a conversation with a licensed insurance agent. Homes with more luxurious finishes or complex construction can expect higher repair costs.
And looking at real world examples…
- The magnitude 6.0 2014 Napa earthquake caused an estimated $1 billion in damage, with individual repairs ranging from $10,000 to $500,000 or more.
- The 2018 Anchorage earthquake even saw newer homes with damage in the hundreds of thousands of dollars owing to varying construction standards and soil conditions.
- The 1989 Loma Prieta earthquake left two blocks of homes on Eighth Avenue in the Sunset District of San Francisco damaged or destroyed and uninhabitable for months due to a landslide on a relatively small slope, even while homes across the street were completely unscathed. This was far from the destruction in the Marina District.
Retrofitting reduces the risk of damage; insurance helps pay for covered damage that still occurs. A retrofit does not guarantee that your home will escape a major loss.
- The Berkeley study found bracing and bolting the modeled stucco homes built prior to the 1980s to current standards can reduce the damage estimate by 65% vs an unretrofitted home.
- Retrofitting typically costs $3,000 – $10,000.
- You might also receive a significant discount on your earthquake insurance premium
What about aftershocks?
Big earthquakes have aftershocks, some of them big and damaging too. Does that mean your deductible resets each time?
Yes and no.
- The CEA counts a quake and all aftershocks within 360 hours (15 days) as one event with one deductible. Other carriers may have shorter windows.
- A carrier can’t cancel your policy before its renewal because of a quake, but your deductible resets if a quake hits beyond the 360 hour window for a CEA policy, or the applicable window for another policy.
In practice you might find yourself and the carrier debating whether damage from a later aftershock was set up by damage from the earlier quake.
How to shop for quake insurance
A good first step is to get a rough sense of what quake insurance might cost for a home like yours.
Our tool lets you get a quick estimate of CEA and other carrier premium costs with no email or phone number required before you have a conversation with your carrier or agent.
While quake policies have similar basic coverage, they vary in how comprehensive they are. For example CEA excludes masonry veneer and limits certain breakables, such as dishes and china, to $500 total with personal-property coverage, while other carriers might.
- For a final CEA quote or to apply, you must go through your current homeowners insurance agent (or your insurer if you buy directly). Your homeowners insurer must participate in CEA. If CEA isn’t available through them, private-market options may be available.
- You should also review quotes and coverage from non CEA options like GeoVera or Palomar. They sometimes have lower rates and broader coverage than the CEA. Those are available through any affiliated agent – you don’t need to go through your homeowners carrier and you don’t need to change your homeowners carrier to qualify.